


- Hospitality segment for FPL showed a strong rebound as RevPAR increased in Europe and Asia Pacific.
- Strong cash flow visibility from recurring income from its properties as well as its pipeline of development projects.
- FPL is expected to deliver ~436,000 sqm of property in 2H FY22 and an additional ~386,000 sqm in FY23.
- Credit profile remains resilient with high fixed-rate debt and low average cost of debt.
- The FPL 4.98% perp looks the most attractive within the real estate space and has an indicative yield to worst of 5.95% with about 1.73 years.
Frasers Property Limited is a multinational real estate developer that is headquartered in Singapore. The company is listed on the SGX-ST Main Board and has total assets of approximately SGD 40.37b as at 31 March 2022.
FY21 financial highlights
For the first half financial results ending 31 March 2022 (“1H22”), revenues for FPL increased by 7.5% to SGD 1.68b. In the last financial year, FPL reclassified a portfolio of industrial and logistics properties in Australia and Europe from properties held for sale to investment properties. FPL had a gain in its financial statements the year prior due to this accounting change. On an adjusted basis, excluding the impact from the gain on change in use, profit before interest and taxation (“PBIT”) for 1H22 was SGD 526.1m as compared to SGD 478.9m in 1H21. Adjusted attributable profit also saw significant growth to SGD 158.2m from SGD 22.5m.
Table 1: PBIT by operating segments
|
Business Segment |
1H22 |
1H21 |
Change |
|
Singapore |
SGD 169m |
SGD 194m |
(13%) |
|
Australia |
SGD 9m |
SGD 24m |
(62%) |
|
Industrial (excluding gain on change in use) |
SGD 207m |
SGD 203m |
2% |
|
Hospitality |
SGD 28m |
(SGD 38m) |
N.M. |
|
Thailand & Vietnam |
SGD 99m |
SGD 67m |
47% |
|
Others |
SGD 47m |
SGD 58m |
(18%) |
|
Source: Company’s presentation, iFAST compilations. |
|||
Singapore and Australia segments saw PBIT falling due to lower contributions from divested properties in Singapore as well as lower level of residential settlements due to the timing of completion of development projects in Australia. Notably, hospitality segment saw a rebound in 1H22, with PBIT increasing to SGD 27.98m as compared to a loss of SGD 38.05m in 1H21.
FPL benefited from the reopening and easing of travel restrictions in the UK. Stronger domestic travel resulted in higher Revenue per Average Room (“RevPAR”). RevPAR in Europe increased from SGD 38 to SGD 158.9 as reservations picked up in early 1Q22 for immediate and forward bookings. RevPAR for Asia Pacific excluding North Asia also picked up from SGD 98.1 to SGD 112.8 due to easing of COVID-19 restrictions in Singapore. Properties in Australia still remained affected during the reported financial period. However, the reopening of Australia’s borders in late Feb 2022 will help to bolster the rebound in hospitality in Australia.
Strong cash flow visibility from properties
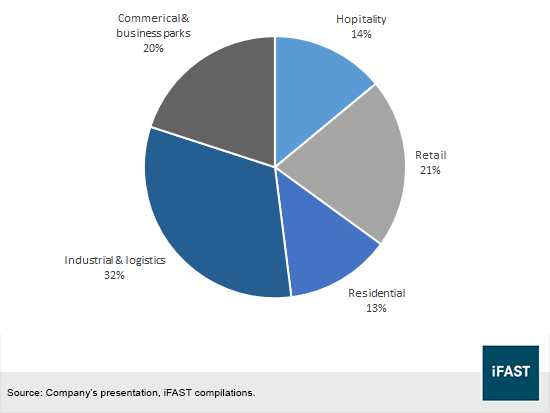
In our previous article on FPL, we noted that FPL had been concentrating their efforts towards industrial and logistics (“I&L”) properties. I&L assets grew from 11% of its total property assets to 31% of its total property assets from 2016 to 2021.
(See related article: Should you buy Frasers Property’s 3.95% perps callable in October 2022?)
The decision to reclassify
I&L properties from held-for-sale properties to investment properties
resulted in an increase in recurring income from rents. Recurring income made
is made up from its I&L, commercial & business parks, hospitality and retail
properties, which made up for 87% of FPL’s total property assets. Recurring
income for 1H22 contributed to 90% of total PBIT. On top of that, FPL’s
property assets provides a good mix and diversity of asset classes, not
contributing to more than one third of its income.
Figure 1: Property assets by asset class
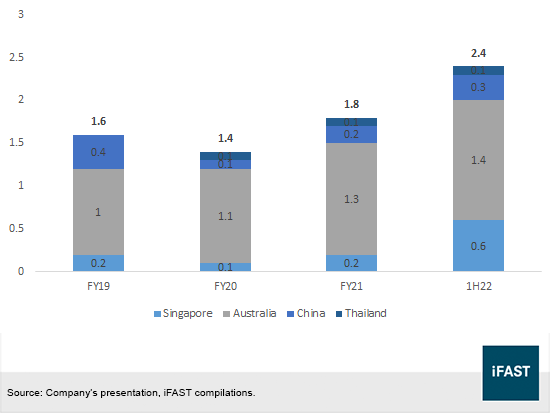
Strong pipeline for FPL for FY22 and FY23 also provides good earnings visibility. FPL is expected to deliver ~436,000 sqm of property in 2H FY22 and an additional ~386,000 sqm in FY23. In 1H22, FPL also has SGD 2.4b in unrecognized revenue for its residential projects (figure 3). Looking forward, as FPL continues to expand in within the I&L space, FPL has ~8.5m sqm of land bank available to carry out further I&L projects in the future.
Figure 2: FPL’s development pipeline
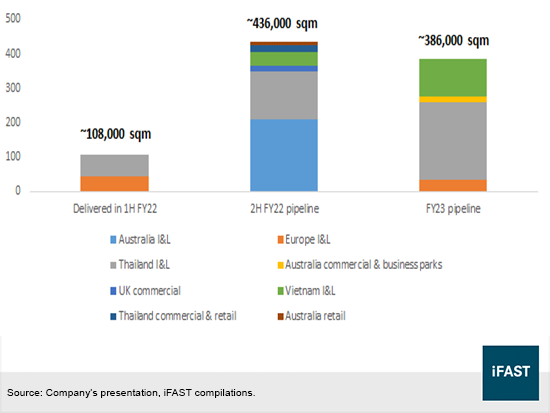
Figure 3: Unrecognised revenue (in SGD m)
Credit profile remains resilient
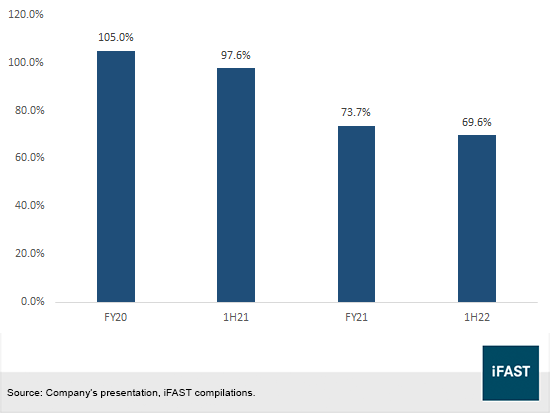
FPL’s credit profile have been improving year over year. Net gearing (net debt-to-equity) improved since FY20 following the divestment of FPL’s stake in in Asia Retail Fund and Frasers Commercial Trust, FPL rights issue and their divestment in Cross Street Exchange. Net gearing was 105% in FY20 and improved to 69.6% in 1H22.
Figure 4: Net gearing (net debt-to-equity)
FPL also had a high proportion of fixed-rate debt at 76.2% and average cost of debt is low at ~2.3% per annum. The high proportion of fixed-rate debt allows FPL to better manage its debt in a rising interest rate environment. Additionally, interest coverage for the company is also high at 3x.
We find FPL’s capital management to be adequate as the management have taken steps to reduce gearing as well as keeping the proportion of fixed-rate debt high. We also expect FPL to refinance some of the expiring debt as it reaches their maturity.
Recommendation
Bond prices of perpetual bonds within the SGD space have seen a broad repricing and are trading below par. This is due to the influx of new issuance of higher yielding perpetual bonds such as the BACR 8.300% Perpetual Corp (SGD) and SOCGEN 8.250% Perpetual Corp (SGD).
For perps closer to their call date such as the GUOLSP 4.600% Perpetual Corp (SGD) and FPLSP 4.380% Perpetual Corp (SGD), these perps do not have their reset dates coincide with their call dates and are also trading below par. This is because it would make more economical sense for the issuer to call back the bonds much later on their reset date where credit and market conditions are much clearer and stable where they can refinance at a much cheaper rate.
We recommend the FPLSP 4.980% Perpetual Corp (SGD) as its reset date coincides with its call date and in addition has a 100 basis points (“bps”) step up margin which makes it more costly for the issuer to not call back the bonds. FPL can refinance this bond with a similar perpetual bond without incurring the step up margin and this makes it less costly for the issuer to do so.
The FPL 4.98% perp has an indicative yield to worst of 5.95% with about 1.73 years to the next call date on 11 Apr 2024. The perp provides the highest yields among comparable real estate perps with similar years to their call date. If not called, the FPL 4.98% perp will reset at the prevailing SGD 5Y SOR plus the initial Spread of 3.040% and the step-up margin of 100 bps.
Table 2: Relative Valuation of FPLSP with other comparable bonds
|
Bond name |
Issuer |
Next Call Date |
Years to next call |
Ask price |
Yield to worst (%) |
|
FPLSP 4.980% Perpetual Corp (SGD) |
Frasers Property Treasury Pte Ltd |
11 Apr 2024 |
1.73 |
98.4 |
5.95 |
|
CAPLSP 3.650% Perpetual Corp (SGD) |
CapitaLand Treasury Ltd |
17 Oct 2024 |
2.25 |
97.8 |
4.71 |
|
WINGTA 4.480% Perpetual Corp (SGD) |
Wing Tai Holdings Ltd |
24 May 2024 |
1.85 |
100.2 |
4.37 |
|
MLTSP 3.650% Perpetual Corp (SGD) |
Mapletree Logistics Trust |
28 Mar 2023 |
0.69 |
99.6 |
4.16 |
|
ALLTSP 5.500% Perpetual Corp (SGD) |
ARA LOGOS Logistics Trust |
01 Feb 2023 |
0.54 |
99.9 |
5.75 |
|
GUOLSP 4.600% Perpetual Corp (SGD) |
GLL IHT Pte Ltd |
23 Jan 2023^ |
0.51 |
97.4 |
10.12 |
|
FPLSP 4.380% Perpetual Corp (SGD) |
Frasers Property Treasury Pte Ltd |
17 Jan 2023* |
0.50 |
98.5 |
7.60 |
|
Source: Bloomberg Finance L.P., iFAST compilations. Data as of 20 Jul 2022. *Reset date on 17 Jan 2028; ^Reset date on 23 Jan 2025 |
|||||
Declaration: For specific disclosure, at the time of publication of this report, IFPL (via its connected and associated entities) holds a position in FPLSP 4.980% Perpetual Corp (SGD), MLTSP 3.725% Perpetual Corp (SGD) and GUOLSP 3.290% 26Oct2026 Corp (SGD) and the analyst who produced this report holds a NIL position in the abovementioned securities.
Our podcast series, Yield Hunters, is available on Spotify, iTunes Podcasts and Google Podcasts. We share our thoughts on new bond issues and hold discussions on the fixed income space. Listen to our latest episode below and follow us!










